Paying online has become routine, but it still deserves a moment of thought, particularly where entertainment spending is involved. Digital financial literacy simply means knowing how online payments work, what information you’re sharing and which controls can help you stay in charge.
For UK adults who choose to use regulated online casino sites, that knowledge is part of sensible consumer protection. It isn’t about becoming a payments expert. It’s about asking a few clear questions before entering any card details: Is this operator properly licensed? Is the checkout secure? Can I see and control what I spend? What happens if I need support?
Here’s a practical way to assess payment security and spending controls without getting lost in technical jargon.
Payment authentication: what a safe checkout should feel like
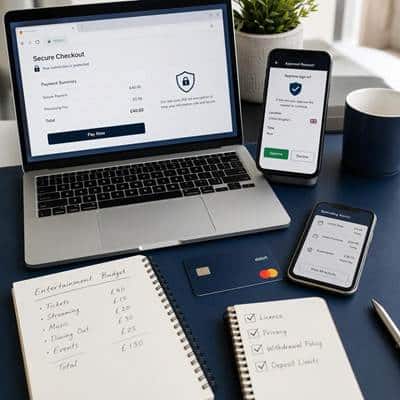
A secure payment journey shouldn’t feel rushed, confusing or secretive. You should be able to identify who is taking the payment, understand the amount being authorised and use a recognised authentication step where your bank requires one.
In the UK, many online payments use Strong Customer Authentication, often shortened to SCA. In simple terms, this adds an extra check to show that it’s really you making the payment. It may involve approving something in your banking app, entering a one-time code or using your device’s biometric security.
The aim is straightforward: make it harder for somebody else to use your payment details without permission.
Signs worth checking before you pay
A trustworthy checkout will usually make the basics easy to spot:
- The web address begins with https:// and your browser shows a padlock icon
- The site’s name and legal company details are available, not buried behind vague wording
- The deposit amount is shown clearly before you confirm
- Your bank’s usual verification screen or app approval appears where relevant
- There are no unexpected requests for passwords, full security codes or remote access to your device
A padlock alone is not proof that a site is trustworthy, mind you. It tells you that the connection is encrypted, not that every policy or operator behind it is sound. Treat it as one useful signal among several.
Keep your own device on your side
Site security and personal security go together. It’s sensible to use a screen lock, keep your browser and operating system updated, and avoid making payments through public Wi-Fi where possible. If you do use a shared device, never save card details or leave yourself logged in.
Phishing is another common problem. A message can look convincing while directing you to a copied website or asking you to “verify” payment details. Rather than following a link in an unexpected text or email, type the operator’s address into your browser yourself, or use a saved bookmark.
Your bank will not normally ask you to share a full password or security code through an unsolicited message. If something seems off, stop there and contact the organisation using details from its official website.
For a plain-language overview of multi-factor payment checks, see the explanation of Strong Customer Authentication.
Choosing a payment method without overlooking the detail
There isn’t one payment method that suits every adult or every situation. The sensible choice depends on how you prefer to track spending, how much information you’re comfortable sharing and which verification process you find clearest.
What matters is that you understand the practical differences before selecting one.
Debit cards
Debit cards are familiar and tend to show transactions directly in your bank account. That can make record-keeping straightforward, since deposits appear alongside your other payments.
Before using one, check:
- Whether your bank provides instant payment notifications
- How the merchant name will appear on your statement
- Whether you can set card controls or transaction alerts in your banking app
- What the operator says about withdrawals and identity checks
In Great Britain, licensed gambling businesses must not accept credit cards for gambling, including via e-wallets funded by credit cards. A debit card is different, but it’s still important not to use money needed for household bills, travel, food or other essentials.
E-wallets
An e-wallet can add a layer between your main bank account and a merchant. Some people prefer this because it can make payment activity easier to separate. Others find that another account means another set of statements and settings to manage.
Check how the e-wallet is funded, whether it has its own authentication process, and whether the operator places any restrictions on deposits or withdrawals using that method. It’s also worth looking at fees, exchange charges where relevant, and transaction-history tools.
Privacy should be understood realistically. An e-wallet may limit which details are passed to the merchant, but it does not make a payment anonymous. Identity checks and regulatory requirements may still apply.
Open Banking payments
Open Banking payments generally let you authorise a transfer through your own bank or banking app. You don’t type card details into the merchant checkout, which some people find reassuring.
You should still check exactly what you’re approving. The bank’s authorisation screen should identify the recipient and amount, and you should only proceed if those match what you expected.
Open Banking can offer a clear route through your existing bank security, but it may not suit everyone. Think about how you’ll monitor transfers, whether you can set alerts and what the site’s withdrawal process looks like. Deposits and withdrawals do not always use identical methods or timescales.
Spending controls: make the boundaries before the payment
The strongest spending control is one you set before you start. It’s much easier to keep a decision when it’s based on a calm plan, rather than a reaction in the moment.
If you choose to take part in gambling activity, treat it as paid entertainment only. Set a separate, pre-defined entertainment budget that does not touch money needed for essential commitments. It should never become a substitute for managing financial difficulties or meeting expenses.
Useful controls to set up
A few small actions can make a real difference to visibility:
- Choose a fixed entertainment amount
- Turn on bank alerts
- Use deposit limits on the site
- Review payment records
- Avoid stored payment details if that suits your habits
- Use time-out or self-exclusion tools when needed
A good rule of thumb is that your payment history should never be a mystery. If you can’t quickly identify the date, amount and merchant for a transaction, take time to investigate it.
Your UK online casino security and consumer-protection checklist
Before opening an account or making a deposit, work through this checklist. It takes only a few minutes and gives you a clearer picture of how an operator handles its responsibilities.
Check the licence
For online gambling offered to consumers in Great Britain, look for the operator’s licence information and verify it through the UK Gambling Commission’s public register. The legal company name on the site should match what you find there.
A licence is important, but don’t stop at the logo in the footer. Check the details yourself.
Read the privacy and data information
Look for a privacy notice that explains:
- What personal data is collected
- Why it is collected
- Who it may be shared with
- How long it is retained
- How you can contact the organisation about your data
Identity verification can feel like an inconvenience, but it is a normal part of regulated services. The site should explain what documents or checks may be required and why. Never send identification documents through an unverified email link.
Look closely at terms and withdrawals
Payment pages should be clear about accepted methods, deposit handling and any relevant processing times. The withdrawal policy deserves equal attention. Read it before paying, not after.
You want clear answers to questions such as:
- How are withdrawals requested?
- Is verification needed before a withdrawal is processed?
- Are there stated processing stages or timescales?
- Can the operator return funds only to the original payment method?
- Where are any fees or restrictions explained?
If the wording is hard to find or leaves too much unanswered, regard that as useful information in itself.
Make sure help is easy to reach
A regulated site should provide visible customer-support routes and a complaints procedure. Check whether there’s an email address, live support channel or telephone option, plus an explanation of how a complaint is handled and escalated.
Also look for safer-gambling tools, including deposit limits, time-outs and self-exclusion options. Independent help is available through GamCare, while GAMSTOP offers a free self-exclusion scheme for participating online gambling businesses in Great Britain.
These services are there for anyone who feels gambling is becoming difficult to manage, or who wants to step back.
Apply the checklist to an age-gated resource
If you’re a UK adult choosing to engage with online gambling, you can practise the checklist on an age-gated destination without treating it as a prompt to participate. Look for payment information, account controls, responsible-gambling tools, privacy notices, identity-verification explanations and support pathways. Keep any spending within a pre-set entertainment budget.
Example resource: Bally Casino’s online-games destination, also available as this casino site.
The point is not to take a site’s claims at face value. It’s to build the habit of checking the detail, using the controls available and keeping your own money decisions clear, calm and firmly within your boundaries.